
Turkish Citizenship by Investment and U.S. Tax: What U.S. Persons Should Know

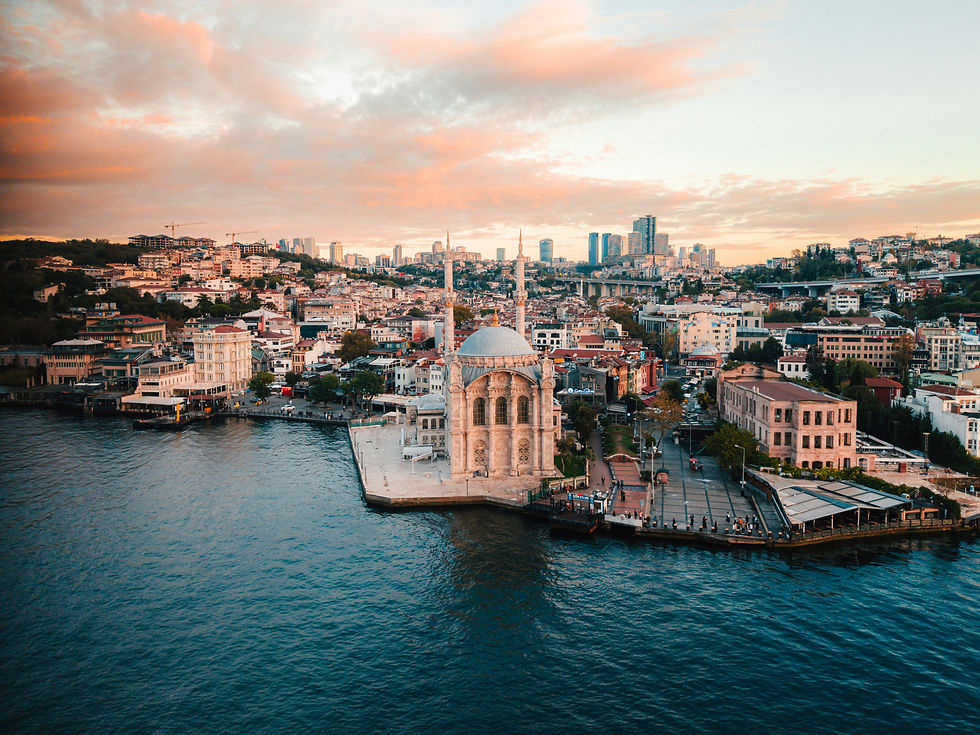
At the Schiff Sovereign Plan B Conference, Panama 2026, held in Panama City from September 17 through 19, 2026, Taymour Polding and Aran Hawker, the co-founders of CIP Türkiye, discussed Türkiye (Turkey) as a Plan B jurisdiction: a second citizenship, a place to invest, and, since June 2026, a place to live under a favorable tax regime. Milan Solarz-Patel, J.D., LL.M. (Taxation), attended the session on behalf of Auric Private Client Advisory LLC and met with both of them in Panama City.
Together the two firms cover the two halves of the same plan. CIP Türkiye handles the Turkish side: the citizenship application, the property, and Turkish tax. Auric Private Client Advisory LLC handles the U.S. side: U.S. tax advice and reporting compliance for U.S. persons who are interested in citizenship, residency, or investment in Türkiye. This post summarizes the program and then explains what it means on a U.S. tax return.
Key Points
Turkish citizenship is available to an investor who buys real estate appraised at US$400,000 or more and holds it for three years.
Under a law published in June 2026, a new Turkish tax resident may qualify for a 20-year exemption from Turkish tax on foreign-source income.
Neither one changes U.S. tax. A U.S. citizen remains taxable on worldwide income, and the Turkish property, bank account, fund, or company each carries its own U.S. reporting.
The Session at the Plan B Conference, Panama 2026
Schiff Sovereign published its recap of the conference to its members on October 6, 2026. According to the recap, Mr. Polding and Mr. Hawker traveled from Istanbul and Bodrum to Panama City, and their firm has already assisted a number of Schiff Sovereign members with the program. They did not walk through a slide deck; they joined Viktorija of Schiff Sovereign for a conversation about what Türkiye offers as a Plan B jurisdiction.
The discussion covered three subjects:
The program. The real estate route, which requires a minimum investment of US$400,000 held for at least three years, and the practical considerations in selecting the right property.
Life in Türkiye. The view of two long-term residents on lifestyle, the real estate market, and the position of the country between Europe, Asia, and the Middle East, including the drawbacks as well as the advantages.
Tax. The tax incentives for foreigners who establish themselves in Türkiye. The principal incentive is now law and is discussed below.
The conference also covered citizenship programs in Argentina and the Caribbean; residency in Colombia, Uruguay, Panama, Argentina, Paraguay, and Mexico; and real estate in Latin America. The full recap, the session recordings, and the presentation slides are available to members of Schiff Sovereign Total Access.
The Turkish Citizenship by Investment Program
The terms below are as presented by CIP Türkiye. The Turkish authorities set the requirements, and the requirements may change.
Item | Terms |
Real estate route | Property appraised at US$400,000 or more, in one property or several, with a three-year restriction on sale recorded on the title deed. CIP Türkiye reports that about 95% of applicants choose this route. |
Other routes | US$500,000 held for three years in a Turkish bank deposit, government bonds, real estate or venture capital fund shares, or fixed capital; or the creation of 50 jobs. |
Family | A spouse and children under 18 are included in the same application. |
Residence | No minimum stay in Türkiye is required for citizenship. |
Dual citizenship | Permitted by Türkiye. The United States also permits it. |
Timing | Typically three to six months for a complete file. |
Mr. Polding and Mr. Hawker stressed that the choice of property decides whether the application succeeds. The appraised value, not the price paid, must meet the threshold; the payment must pass through a Turkish bank; and the property must be free of encumbrances and must never have been owned by a foreigner. For that reason, CIP Türkiye generally places clients in new construction purchased from the developer.
Readers who are comparing programs may find the free Citizenship by Investment Calculator published by Schiff Sovereign useful.
Türkiye's New 20-Year Tax Exemption
According to EY's summary of Law No. 7582, the law was published in the Official Gazette on June 4, 2026, and exempts the foreign-source income and gains of a new Turkish tax resident from Turkish income tax for 20 years. EY reports two conditions: the individual must become a Turkish tax resident on or after January 1, 2026, and must not have had residence or tax liability in Türkiye during the three preceding calendar years. Turkish-source income remains taxable in Türkiye.
Two points deserve attention. First, citizenship and tax residence are separate. Citizenship requires no stay in Türkiye; the exemption requires the individual to become a Turkish tax resident. Second, the exemption is not automatic. As CIP Türkiye notes, eligibility depends on residence history, the source of the income, and timing, and the analysis must be completed before Turkish tax residence begins.
A Second Passport Does Not Change U.S. Tax
The United States taxes its citizens and permanent residents (i.e., green card holders) on worldwide income wherever they live. Turkish citizenship does not change that, and neither does Turkish tax residence.
The 20-year exemption removes Turkish tax. It does not remove U.S. tax. The U.S.–Türkiye income tax treaty preserves the right of the United States to tax its own citizens. Because Türkiye does not tax the exempt income, no foreign tax credit arises, and the U.S. tax on that income is due in full. For a U.S. citizen who moves to Türkiye, the value of the exemption is that Türkiye does not add its own tax on income from outside Türkiye.
A U.S. citizen who lives in Türkiye may still reduce U.S. tax in the usual ways: the foreign earned income exclusion (Form 2555) for earned income, and the foreign tax credit (Form 1116) for Turkish tax paid on Turkish-source income, such as rent from the Turkish property.
Only expatriation ends U.S. taxation of worldwide income. A second citizenship is a prerequisite, and renunciation brings Form 8854 and a possible exit tax. That planning belongs at the start, not at the end. Our earlier post covers the U.S. side of a Plan B.
Turkish Real Estate on a U.S. Tax Return
Rent. Rental income is reported on the U.S. return each year, in U.S. dollars. The building is depreciated over 30 years, and Turkish income tax paid on the rent may be claimed as a foreign tax credit.
Sale. Gain on a sale after the three-year hold is measured in U.S. dollars; thus, a change in the exchange rate affects the U.S. result. A mortgage in Turkish lira can produce a separate currency gain when it is repaid.
Reporting. Real estate held directly in the name of an individual is not reported on the FBAR or on Form 8938. Real estate held through a company or a trust is different: the entity is reported.
Turkish Accounts, Funds, and Companies
Bank account. Every route runs through a Turkish bank account. A U.S. person reports the account on FinCEN Form 114 (FBAR) once total foreign accounts exceed US$10,000, and on Form 8938 above higher thresholds. Under the bank deposit route, the interest is taxable in the United States.
Fund shares. A Turkish real estate or venture capital fund is generally a passive foreign investment company (PFIC) for a U.S. investor. PFIC status brings Form 8621 and an unfavorable default tax regime. This route should be reviewed before the investment is made.
Turkish company. A U.S. person who forms or buys into a Turkish company files Form 5471 or Form 8858, depending on how the company is classified for U.S. tax purposes, and may be taxed currently on its income.
Penalties for missed information returns are substantial and can apply even when no tax is due.
Estate, Gift, and Family Considerations
The United States taxes the worldwide estate of a U.S. citizen, including property in Türkiye. No estate and gift tax treaty exists between the United States and Türkiye; relief from double tax comes from the U.S. credit for foreign death taxes.
Türkiye imposes its own inheritance and gift tax. According to the EY summary, Law No. 7582 reduces the rate to 1% on qualifying inheritances for individuals within the new regime.
A spouse who is not a U.S. citizen does not qualify for the unlimited marital deduction, which calls for a qualified domestic trust (QDOT) or other planning. Our Q&A with Schiff Sovereign on estate planning and asset protection covers this subject in more detail.
A U.S. person who receives more than US$100,000 in gifts or bequests from a family member who is not a U.S. person reports them on Form 3520.
CIP Türkiye notes that Türkiye is an E-2 treaty country. That point matters to a family member or business partner who is not a U.S. person and who wishes to enter the United States as a treaty investor. Since December 2022, a person who acquired treaty-country nationality by investment must first have been domiciled in that country for three continuous years. This point should be confirmed with appropriate immigration counsel.
How Auric Private Client Advisory LLC Can Help
Auric Private Client Advisory LLC provides U.S. tax advice and reporting compliance to U.S. persons who are considering Turkish citizenship, Turkish residency, or an investment in Türkiye. The work is most valuable before the investment is made: selecting the route, deciding how the property will be held, and determining what a move to Türkiye would mean on the U.S. return. The Turkish side belongs with Turkish advisers such as Taymour Polding and Aran Hawker at CIP Türkiye.
If you are a U.S. person considering Turkish citizenship, residency, or investment, contact Auric Private Client Advisory LLC to review the U.S. tax and reporting before you commit: https://www.auricllc.com/contact
The program terms above are drawn from the materials presented by CIP Türkiye at the Schiff Sovereign Plan B Conference, Panama 2026, and from cipturkiye.com. Our thanks to Taymour Polding, Aran Hawker, and the Schiff Sovereign team.

Comments